Mortgage Blogs
Stay up to date with the recent industry news and mortgage trends.
Are New Federal Housing Rules Giving Fall Buyers an Advantage in Alberta?
Are New Federal Housing Rules Giving Fall Buyers an Advantage in Alberta?
National mortgage updates are changing how Canadians buy real estate this fall. While expanded rule frameworks impact buyers across Canada, their effect is especially powerful in Alberta. As families from British Columbia and Ontario continue relocating to Western Canada for lower housing costs, a booming job market, and zero provincial sales tax, these federal adjustments provide even greater leverage. Whether you are moving to Alberta, buying a secondary property, or expanding a rental portfolio, understanding these fall policy shifts is essential.
How Extended Amortizations Fuel Alberta's Housing Surge
The federal decision to offer 30-year amortizations for all first-time home buyers and anyone purchasing a newly constructed property directly aligns with Alberta's expanding real estate market. Cities like Calgary, Edmonton, Red Deer, and Lethbridge are experiencing steady growth in new residential developments.
Stretching repayment terms from 25 to 30 years lowers monthly mortgage payments, helping buyers manage household cash flow effectively. In Alberta's active new-construction market, this option allows buyers to secure larger floor plans or modern energy-efficient homes without straining monthly budgets.
New Construction Focus: Buyers of new builds qualify for 30-year amortizations regardless of whether they have owned property previously, making it ideal for move-up buyers in expanding Alberta communities.
Increased Monthly Cash Flow: Lower mandatory monthly payments increase financial flexibility, allowing families to allocate funds toward savings, business ventures, or lifestyle pursuits.
Relocation Support: Out-of-province buyers relocating from Vancouver or Toronto can secure high-quality detached homes in Alberta while maintaining comfortable monthly carrying costs.
Leveraging the $1.5 Million Insured Cap for Relocation and Investment
The federal insured mortgage price cap increase from $1 million to $1.5 million fundamentally changes down payment requirements. Previously, buying a home above $1 million required a full 20% down payment. Under the updated structure, buyers can put down 5% on the first $500,000 and 10% on the remaining balance up to $1.5 million.
For families selling high-value properties in BC or Ontario and moving to Alberta, this policy provides major strategic choices. Buyers can purchase luxury properties in prime Alberta neighborhoods with lower upfront cash requirements, keeping capital free for secondary market investments.
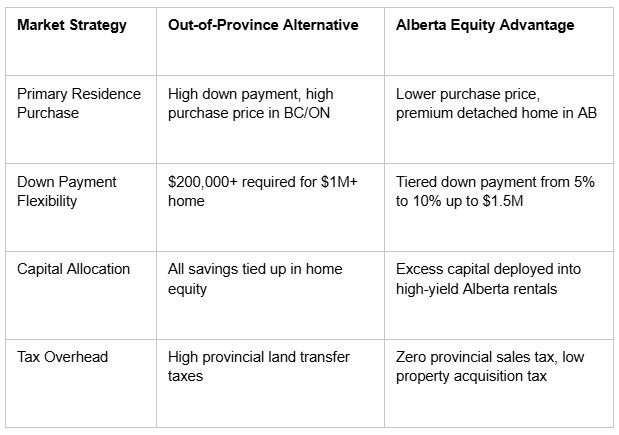
This framework makes Alberta attractive not only for personal residences but also for real estate investors building multi-unit or single-family rental portfolios in secondary markets like Airdrie, Cochrane, and Medicine Hat.
Navigating the Stress Test and Debt Restructuring in Western Canada
Even with expanded price caps and longer amortizations, the federal mortgage stress test remains in full effect. Borrowers must prove they can manage payments at their contract rate plus 2% or 5.25%, whichever is higher. Lenders evaluate applications using strict Gross Debt Service (GDS) and Total Debt Service (TDS) ceilings.
At Merge Mortgage Group, our team works with clients across Alberta, BC, and Ontario to navigate these qualification hurdles smoothly.
Debt Consolidation: Rolling high-interest credit card debt, auto loans, or personal lines of credit into your mortgage lowers your overall TDS ratio, immediately increasing your home purchasing power.
Straight-Switch Protection: Uninsured homeowners switching lenders at renewal without increasing loan balances can bypass stress-test re-qualification, ensuring competitive interest rate negotiations.
Custom Investment Planning: We help investors structure financing across multiple properties, using home equity from existing assets to acquire cash-flowing Alberta real estate.
Alberta Housing Advantage Matrix
Evaluating federal updates alongside Alberta's economic fundamentals highlights why fall is an ideal time to act.
Evaluate Relocation Potential: Compare housing costs, tax savings, and career growth in Alberta against your current province to determine overall savings.
Review Amortization Eligibility: Check if your purchase qualifies for 30-year terms under first-time buyer or new construction guidelines.
Optimize Credit Ratios: Restructure consumer debt to ensure GDS and TDS ratios fall comfortably within federal approval guidelines.
Work with Regional Specialists: Partner with licensed mortgage agents who understand interprovincial moves, Alberta secondary markets, and custom financing solutions.
Ready to take advantage of Alberta's housing opportunities this fall? Connect with our expert team at mergemortgage.ca today to schedule your comprehensive mortgage consultation.
📍Serving Alberta, BC, Ontario and SK
🌐 mergemortgage.ca
Trusted Guidance, Proven Success
Kristen Young | Mortgage Broker
(403) 589-4708
Assistance Hours
Monday to Sunday: 7:00am – 9:00pm
Address
356 Cranston Road Se, Calgary Alberta T3M 0S0
Get In Touch With
(403) 589-4708
Assistance Hours
Mon – Fri 9:00am – 8:00pm
Saturday/Sunday – CLOSED
Contact Us


© 2026 Merge Mortgage Calgary - All Rights Reserved.
Kristen Young, Mortgage Broker
BRX Mortgage Inc